Reduce Fleet Insurance Costs: How to Control Claims and Document Risk Improvement
Insurance expenses are only part of the financial impact of fleet incidents. However, claims management, driver safety, and documented corrective action can help transportation companies understand losses and strengthen their risk management processes.
Effective fleet insurance risk management starts before a claim occurs. By identifying recurring loss patterns, investigating incidents, and verifying corrective action, fleets can address preventable risks and build a clearer record of safety improvement.
Commercial fleet insurance helps protect transportation businesses against significant financial exposure. Nevertheless, the consequences of an incident can extend far beyond the claim itself. Vehicle repairs, deductibles, downtime, disrupted deliveries, and administrative work can all affect operational performance.
For fleet managers, the objective is not simply to find a lower premium. Instead, it is to understand what drives losses, strengthen controls, and document how the organization responds to risk. A structured approach to fleet claims management can therefore support better decisions and clearer communication about risk improvement.
1. Understand What Drives Fleet Insurance Costs
Fleet insurance costs are influenced by several factors, including loss history, claim frequency and severity, vehicle types, operating conditions, coverage requirements, and broader insurance market conditions. Although not every factor is within a company's control, managers can investigate the operational issues contributing to preventable losses.
Start by reviewing recent claims alongside fleet size, mileage, vehicle use, and route conditions. In addition, look for changes over time. This comparison can help management identify where stronger controls may be needed and distinguish operational risks from pricing factors that should be discussed with a broker or insurer.
- Collision frequency: Repeated incidents may reveal unresolved driver, vehicle, or operational risks.
- Claim severity: Significant collisions can lead to extensive repairs, liability exposure, and prolonged downtime.
- Driver behavior: Recurring unsafe driving patterns may indicate opportunities for targeted coaching.
- Vehicle condition: Maintenance deficiencies can contribute to incidents and increase operating expenses.
- Documentation quality: Incomplete incident records can make investigations and claims handling more difficult.
- Risk control effectiveness: Policies and training must translate into consistent practices and verified improvement.
Reviewing these factors together provides a more useful picture than looking at premiums alone. As a result, managers can prioritize risks they can address internally while preparing more informed discussions with their insurance representative.
2. Analyze Claims History to Identify Recurring Losses
A claims history should be treated as a source of operational intelligence, not simply a record of past incidents. For example, reviewing multiple claims may reveal patterns involving vehicle types, routes, backing maneuvers, driving behavior, or recurring operating conditions.
Repeated backing incidents may indicate a need to review yard procedures, driver training, visibility, or vehicle positioning. Similarly, several incidents involving following distance may point to opportunities for targeted coaching and follow-up. Therefore, look for shared circumstances rather than treating every event as an isolated case.
A useful claims review should examine:
- Frequency: How often are incidents occurring?
- Severity: Which losses have the greatest financial impact?
- Recurrence: Are similar incidents happening repeatedly?
- Contributing factors: Which driver, vehicle, route, or operating conditions were involved?
- Previous interventions: Were corrective actions completed, and did similar events continue?
Where possible, compare incident trends against fleet size, mileage, and other appropriate exposure measures. Otherwise, a raw incident count may be misleading when fleet activity changes over time.
Look Beyond the Individual Claim
A single incident requires an appropriate response. However, repeated incidents call for a broader investigation into the conditions that may be creating the same risk. Identifying those patterns is a critical step toward more effective loss prevention.
3. Strengthen Fleet Claims Management and Documentation
When an incident occurs, a clear reporting process helps the organization preserve relevant information and coordinate follow-up. Without defined responsibilities, teams may overlook important evidence or delay notifying the appropriate parties.
For that reason, transportation companies should establish procedures covering driver reporting, evidence preservation, internal notification, claim submission, and follow-up. These procedures should reflect applicable requirements and the company's insurance policy.
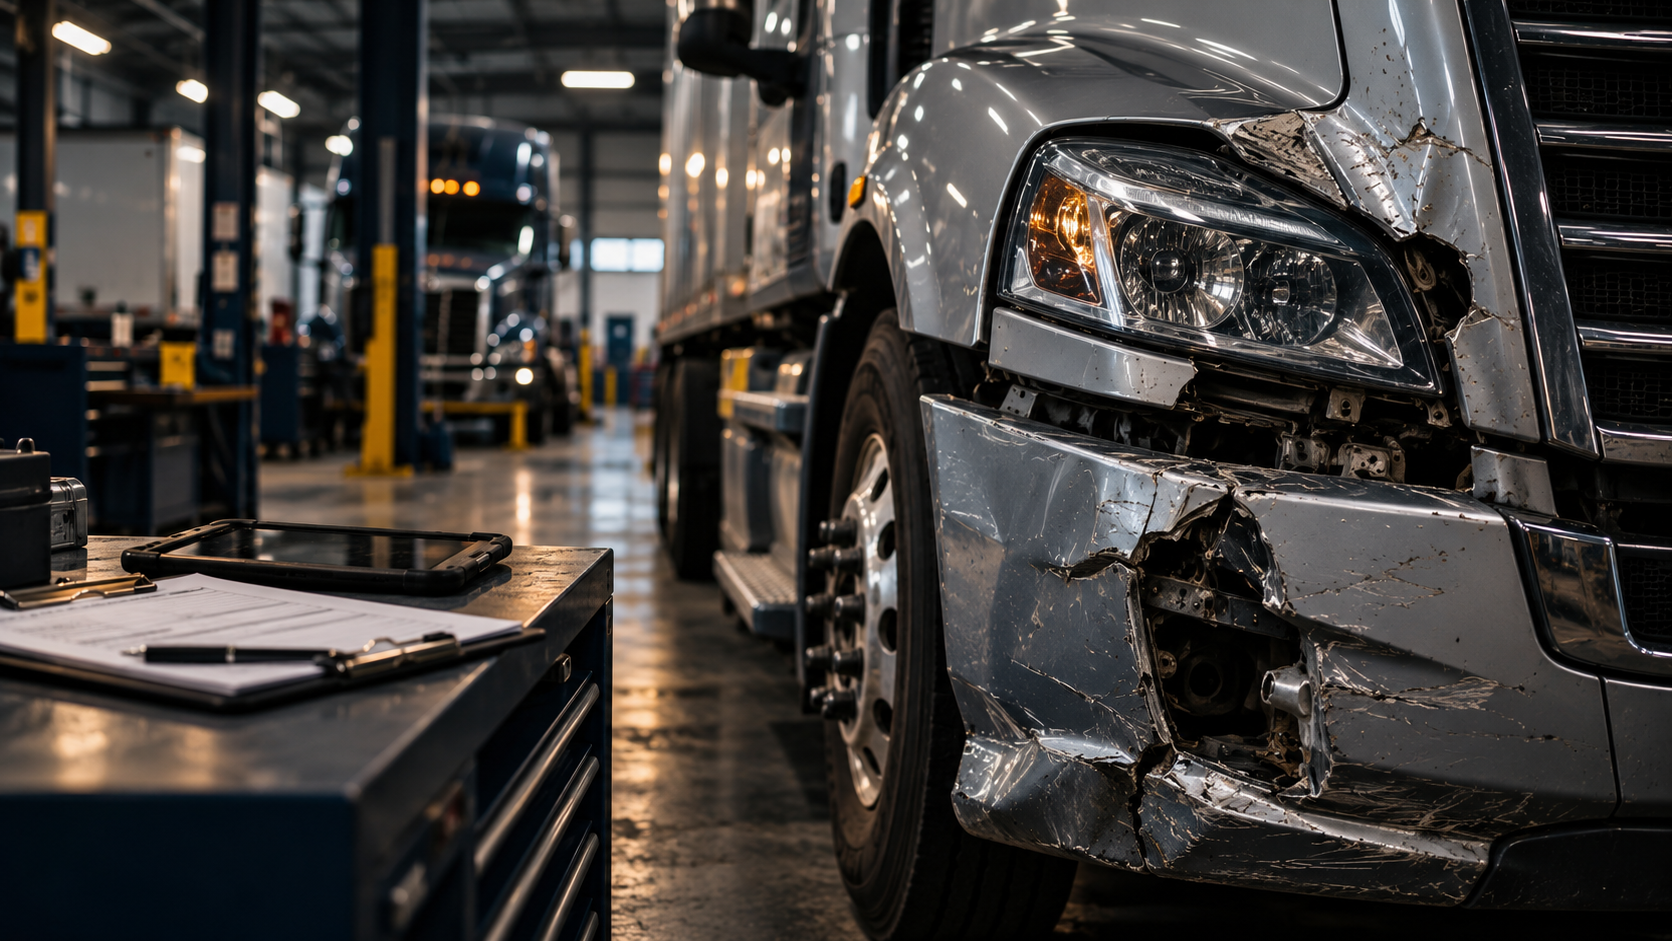
A structured process should include:
- Prompt reporting through the company's established incident procedures.
- Photographs, witness information, and other relevant evidence when available and appropriate.
- Accurate records of the incident's time, location, circumstances, and known consequences.
- Timely notification to the insurer or designated claims administrator according to applicable requirements.
- Secure retention of relevant driver, vehicle, maintenance, and incident records.
- Clear responsibility for outstanding documentation and open claims.
Keep documentation factual, consistent, and appropriately secured. In addition, preserve original records and follow established procedures for required reports or statements. Never alter records to make an incident appear more favorable.
Well-organized information can help management understand incidents, identify recurring issues, and communicate more effectively with claims professionals. It also provides a foundation for evaluating whether corrective measures are addressing the underlying causes of loss.
4. Connect Driver Safety to Loss Prevention
Driver safety programs can help address behaviors and conditions that contribute to preventable incidents. However, collecting safety alerts or documenting a training session is not enough. Management needs a process that turns observations into appropriate interventions and follow-up.
Depending on the findings, interventions may include:
- Targeted coaching for recurring speeding or unsafe following distance.
- Additional instruction for backing, parking, and low-speed maneuvers.
- Review of fatigue risks and unrealistic scheduling pressures.
- Investigation of repeated harsh-braking events and other relevant driving patterns.
- Review of maintenance issues, route conditions, and operating procedures.
- Follow-up evaluations to determine whether performance has improved.
At the same time, consider the circumstances surrounding each event. Traffic, weather, road conditions, equipment, and workload can influence driving behavior. By reviewing these factors, managers can distinguish isolated events from recurring problems that need intervention.
5. Document Risk Improvement for Insurance Renewal
Transportation companies may introduce new procedures, improve driver coaching, or strengthen incident reporting without maintaining a clear record of the work completed. As a result, it can be difficult to evaluate the impact of those initiatives or explain the process during renewal discussions.
Documented risk improvement gives management a more reliable way to evaluate safety initiatives and present relevant information to an insurance broker or carrier. For example, retain training logs, revised procedures, investigation findings, and follow-up reviews.
Consider tracking these indicators:
- Collision frequency and severity over time.
- Recurring incident types and their contributing factors.
- Driver coaching and training completion.
- Corrective actions completed by their assigned deadlines.
- Repeat incidents following an intervention.
- Maintenance deficiencies identified and resolved.
- Improvements in reporting completeness and investigation procedures.
Where appropriate, compare results before and after an intervention while accounting for changes in fleet size, mileage, routes, and operating conditions. Consequently, the comparison is more meaningful and less likely to confuse increased activity with poorer performance.
This information can help a broker or insurer better understand the organization's risk management efforts. Nevertheless, documented improvement does not guarantee lower premiums, more favorable coverage, or a particular underwriting decision. Those outcomes depend on the insurer's evaluation, policy terms, and market conditions.
6. Turn Corrective Action Into Measurable Results
A common weakness in risk management is treating a meeting, training session, or incident report as the end of the process. Instead, the key question is whether the identified risk has actually been addressed.
- Identify the finding. Document the incident, relevant evidence, and contributing factors.
- Determine the response. Select an appropriate action, such as driver coaching, maintenance, or a procedural change.
- Assign responsibility. Establish an accountable owner and a reasonable completion deadline.
- Verify completion. Record the action taken and retain supporting documentation.
- Evaluate the outcome. Review subsequent performance to determine whether the concern has decreased or requires further action.
For example, if a fleet experiences recurring backing incidents, management might revise backing procedures and provide targeted instruction. Afterward, the team should check whether drivers follow the procedures and whether similar incidents continue.
If the risk persists, adjust the original intervention. Likewise, if similar problems affect multiple drivers, examine broader training, scheduling, equipment, or supervision practices.
7. Evaluate the Total Financial Impact of Fleet Losses
Insurance premiums represent only one part of the financial consequences associated with fleet incidents. Depending on the circumstances, a collision can also create repair expenses, deductibles, vehicle downtime, replacement vehicle costs, disrupted deliveries, cargo losses, and administrative work.
Some expenses may be covered by insurance, subject to policy limits, deductibles, exclusions, and conditions. However, other costs may remain with the transportation company. Tracking these expenses consistently helps management understand the broader impact of incidents.
Management should ask:
- Which incident types create the greatest total operational impact?
- How much downtime follows significant incidents?
- Are repeated claims associated with the same underlying weaknesses?
- Which preventive measures deserve additional resources?
- Are incident costs, corrective actions, and outcomes being tracked consistently?
This broader view can help leaders prioritize safety investments and evaluate operational improvements. Ultimately, the objective is to reduce preventable losses while maintaining appropriate insurance protection and reliable fleet operations.
8. Fleet Risk and Claims Management Checklist
Use this checklist to assess whether your current processes support consistent incident management and documented risk improvement.
- Review claims history for recurring causes and severity patterns.
- Monitor relevant driving indicators and investigate significant events.
- Maintain clear incident reporting and evidence preservation procedures.
- Assign responsibility for claims follow-up and outstanding documentation.
- Provide targeted driver coaching and document completed interventions.
- Track corrective actions, deadlines, and verification results.
- Review vehicle maintenance and operating procedures for recurring weaknesses.
- Compare risk indicators over time using appropriate exposure measures.
- Maintain records of safety initiatives and measurable outcomes.
- Discuss relevant risk improvements with your insurance broker before renewal.
- Periodically review whether your insurance coverage remains appropriate.
A documented safety program is more than a collection of policies. Instead, it connects risk identification with accountable action, supporting evidence, and follow-up so management can evaluate what is actually improving.
Conclusion: Reduce Fleet Insurance Costs Through Better Risk Control
Transportation companies cannot control every factor that influences insurance pricing. Nevertheless, they can take a more disciplined approach to identifying preventable risks, managing claims, and documenting improvements.
Effective fleet claims management connects incident reporting with investigation, driver coaching, corrective action, and measurable follow-up. In turn, it helps management understand where losses originate and which interventions deserve priority.
By maintaining consistent records and reviewing outcomes, transportation leaders can strengthen internal oversight and communicate their risk management efforts more clearly. Although insurance savings are not guaranteed, an evidence-based process gives management a stronger foundation for operational and renewal discussions.
How Clearly Can You See Your Fleet's Risk?
GLD Systems helps transportation organizations evaluate safety, compliance, driver performance, and operational risk. Identify where stronger oversight, clearer documentation, and consistent corrective action may improve your current risk management process.
START YOUR RISK ASSESSMENT →Anticipate. Mitigate. Eliminate Risk.
This article provides general fleet risk management information and does not constitute insurance, legal, or financial advice. Insurance coverage, premiums, and renewal terms are determined by the relevant insurer and policy conditions.